Private property mortgage investor in Thailand — 9-15% per year
“If they stop paying,
what happens then”
This is the rate under the contract, not a guaranteed return · Investment carries risk. Investors should study the information before deciding.
We answer the question above clearly first, and talk about the numbers afterwards — because if the plan for a default is not clear, this number means nothing.
- Every deal is secured by a title deed registered at the Land Office done in front of an officer
- We keep the amount at a level the borrower can repay rather than pushing it as high as possible (The amount is set from our team’s valuation against real market data · The ratio differs with the type and location of the property.)
- See the instalments that actually arrive in your own portal no need to call the team
Detached house with land · surrounding provinces
Thisis not a depositand there is no protection of principal · The money investedstays in the contract for its whole term and cannot be withdrawn midway · If the borrower stops paying, the mortgage is enforced through the court to have the property sold and that takes time and may not fetch what the property was valued at
If the borrower does not redeem how we handle it
We do not wait until the due date and then start thinking about it — the plan starts before the money goes out
We keep the amount at a level that can be repaid
Our own valuation team does the work, compares real market prices, then sets the amount meaningfully below the appraised value The goal is for the borrower to be able to repay, not for the amount to be as high as possible because a deal that ends with the property lost is a deal both sides lose
We follow every instalment rather than waiting for the due date
A team follows the instalments due for the whole term, and you can open the portal and check at any time If an instalment slips, you know from the first late one not at the end of the term
We negotiate before the deadline
If the borrower tells us straight before the deadline, we look for a way out immediately — extend the contract · find new funding to close it · or help market and sell the property before the term ends so that you get your money back and the borrower still has something left to start again with
The property is yours, and we help sell it
Under a sale with right of redemption, ownership has been yours since the day of transfer. Once the deadline passes with no redemption, we bring in the same marketing team and channels we use to sell property normally to help sell it — but selling takes time, and the price achieved depends on the market at that time We do not guarantee that it will sell within any period or at any particular price
Once you have invested,you should be able to sleep
If investing keeps you awake, better not to invest yet
We lay out the default plan, the margin and all the limitations
not to make you decide faster — but so that youdecide to invest and then do not worry all year
We would rather hear “not yet” than “yes” followed by a year of anxiety at every instalment
If a mortgage borrower stops paying what we do for you
A mortgage is different from a sale with right of redemption: ownership does not transfer to you. The property stays in the borrower’s name and you hold the rights of a mortgagee registered at the Land Office.
Once payments fall behind as the contract defines the lender has the right to enforce the mortgage. In practice, once payments are two consecutive months behind, we start the process for you — you are not left to chase it yourself.
A written notice is sent as the law requires, giving the borrower time to pay first. Many cases end here, with the borrower resuming payment or redeeming.
If the deadline passes and there is still no payment, you have two routes — we arrange a lawyer and handle it for you under a power of attorney you grant, at a cost agreed beforehand; or you handle it yourself and we prepare the documents for you.
Interest under the contract keeps running until the case ends — it does not stop on the day the borrower stopped paying.
Money from the public auction goes to the outstanding principal and interest in the order the law sets.
What we do not guarantee — court proceedings take a long time, and the money from a public auction depends on what a bidder actually pays, which can be below the appraised value. We do not guarantee that you will recover the principal and interest in full, and we do not guarantee how long it will take.
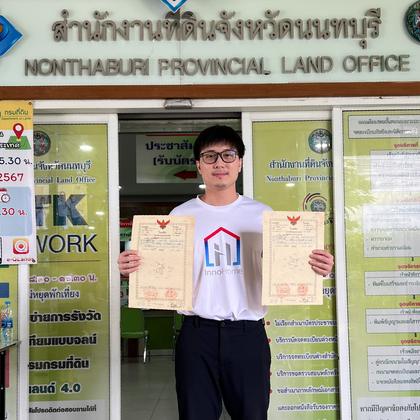
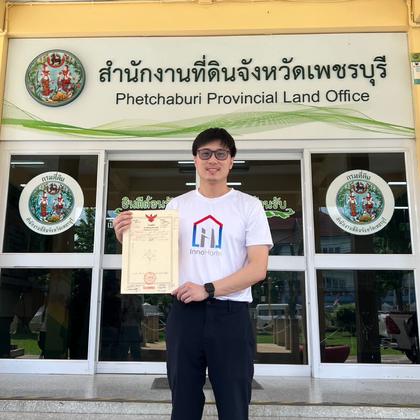
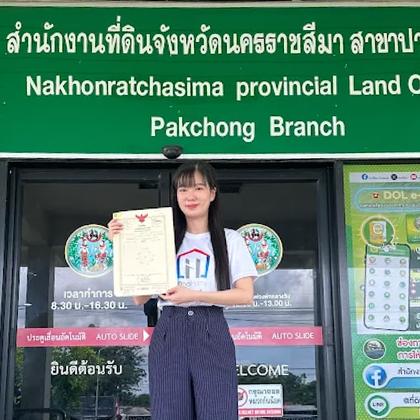
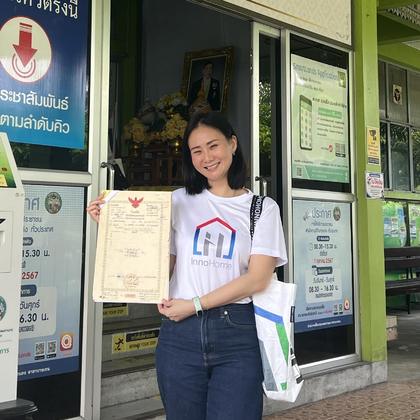
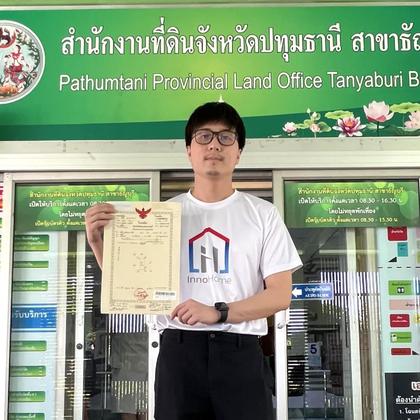
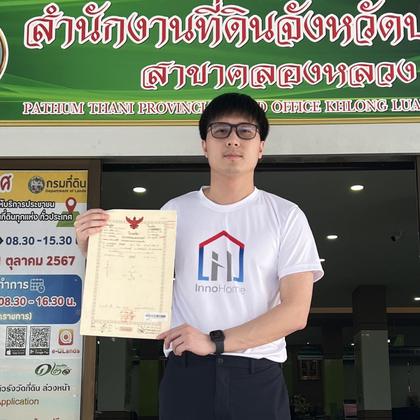
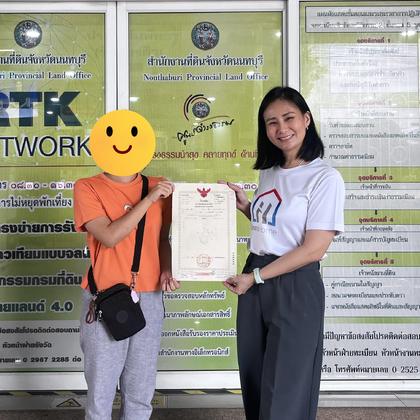
Every deal is registered at theLand Office in front of an officer
No signing between ourselves at an office or a coffee shop — the team travels to the Land Office of the province where the property is, every time. The photos below are from real transfer days in several provinces.
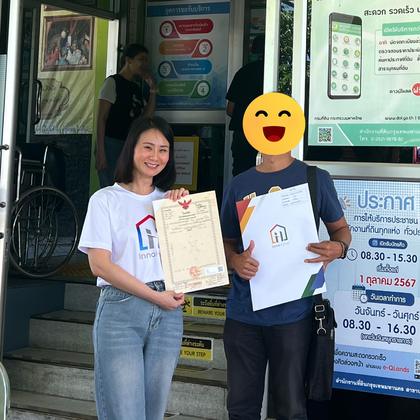
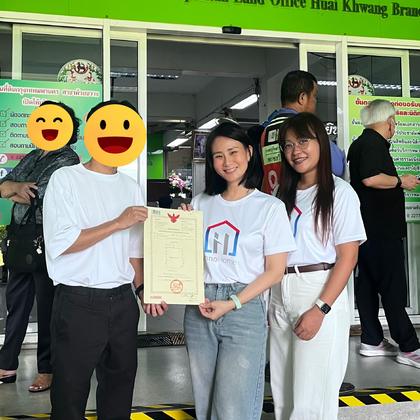
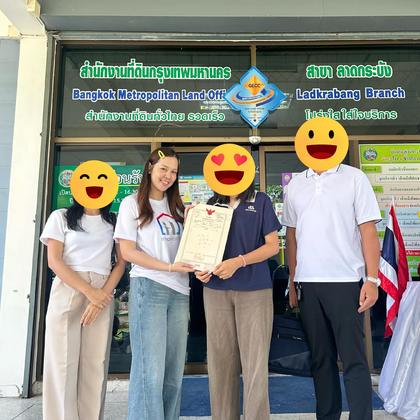
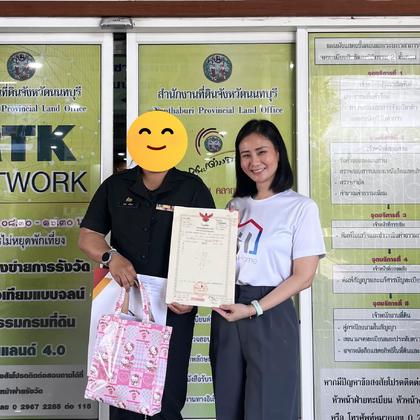
Clips fromour real work
The same clips that are on InnoHome’s YouTube channel — not re-cut for this page
The numbers are inthe real deals not in the headline
Every deal shows the same set of specifications, so you can compare immediately — the examples below are illustrative data to show the format
The return shown is the rate under the contract not a guaranteed return · The actual return depends on the borrower’s payments
Take the return3-12 months in advance
No need to collect it month by month — you can choose to deduct the return in advance from the money you have to bring on transfer day. That means less actual cash from day one, and the instalments deducted count as already received, with nothing to chase.
Not every deal deducts the same — the number of months that can be deducted depends on what is agreed with the borrower in each deal, and is stated in that deal’s valuation book
If the property is lost how much margin is left
We lend well below the appraised value depending on the property and the case — the remaining margin is your buffer if the property has to be sold
| Example property | Appraised value | Amount lent | Return per year | Margin if it has to be sold |
|---|---|---|---|---|
| Condominium, Bangkok | ฿2,000,000 | ฿1,000,000 (50%) | 12% | ฿1,000,000 |
| House with land, surrounding provinces | ฿4,000,000 | ฿2,000,000 (50%) | 15% | ฿2,000,000 |
| Vacant land, other provinces | ฿8,750,000 | ฿3,500,000 (40%) | 13% | ฿5,250,000 |
| Townhouse, surrounding provinces (illustrative) | ฿3,000,000 | ฿1,200,000 (40%) | 12% | ฿1,800,000 |
Limitations you still have to accept — we do not hide them
- The margin is a starting figure, not a guaranteed profit — the price actually achieved depends on the market on the day of sale, and there are selling costs to deduct
- Selling a property takes time — land in other provinces can take far longer than a condominium in the city
- The money is tied up during the contract — it cannot be withdrawn midway. If you may need this money within 1 year, you should not invest it
- If the borrower does not cooperate exercising your legal rights may have to go through the court, which takes time and costs money
- The margin is not the same in every deal — how far below the appraised value we lend depends on the property and the case A deal lent at the upper end leaves a smaller buffer which may not cover the cost of selling if the market is poor. The real figures for that deal are in the valuation book, which you can read before deciding.
- You cannot use the property during the contract — you hold a registered mortgage over the property as security, but the owner keeps the property and keeps living in or using it as normal
The taxan investor needs to know before filing next year
Interest from a property mortgage is income under Section 40(4)(a), and it has its own rules — many people assume it is taxed like a capital gain and file the wrong way, so we summarise the approach based on Revenue Department rulings for you to read first, so you can prepare the documents from the first day you lend, rather than hunting for them in March.
when the mortgage is registered at the Land Office
The registration fee here is paid bythe borrower You have nothing to file at this point
The borrower paysWhile the contract is running
The interest you receive is taxable income for that year — andthe deal’s documents are in the portal to download at any time no need to keep your own file
Record the interest receivedThe principal comes back to you
The interest received isincome under Section 40(4)(a) File it with P.N.D.90 in January-March of the following year No expense deduction is allowed
You are the one who filesIf enforcement ends in a court-ordered auction
You are repaidfrom the auction proceeds up to the amount secured by your mortgage. A foreign investor cannot hold ownership of land in Thailand, so this route ends in a sale, not in the property being transferred to you
The court handles the saleTaking a mortgage — collecting interest
- Interest received = income under Section 40(4)(a) Filed together in P.N.D.90 (January-March of the following year)
- Expenses cannot be deducted — tax is calculated on the full interest received
- Interest may be charged atno more than 15% per year under Section 654 of the Civil and Commercial Code
- If you lend as a regular business (several borrowers, continuously) you must pay specific business tax of 3.3% of the interest Register Por.Thor.01 within 30 days and file Por.Thor.40 every month — a single loan is not liable
If the borrower defaults — what you can and cannot do
- A mortgage does not transfer ownership to you the title deed stays in the borrower’s name with your mortgage registered on it — you cannot simply take the property and you cannot sell it yourself without the borrower’s agreement or a court order
- Interest may not exceed 15% per year under Section 654. If the rate agreed is higher, the whole interest is void, not just the excess. Your annual filing stays P.N.D.90 for every year of the contract
- The mortgage registration fee is 1% of the amount — paid by the borrower at the Land Office, not by you
- We negotiate long before the deadline, so most cases never reach the court
- If you do end up owning the property and resell within 5 years specific business tax is due 3.3% paid at the Land Office on transfer day — a foreign investor can own a condominium unit within the foreign quota, but not land
3 things people get wrong most often — read before planning your tax
- Keep a record of the interest received on every deal — because tax is calculated on the full interest, as shown above, andno expense deduction is allowed your filing has to match what actually came in
This part we already handle for you — every document for a deal done with InnoHome is in theinvestor portal download it yourself at any time even after the contract has ended All that is left is to have an accountant review your portfolio before you file - The term “regular business” has no fixed number of borrowers — it is judged on behaviour, on whether you lend continuously as an occupation. If you do several deals back to back in one year, you should assess specific business tax at the start of the year, not wait to be assessed retrospectively.
- A large portfolio may be better held through a company — the point where it starts to be worthwhile is around 3 million baht of interest received per year (roughly 20 million of principal at 15%) This is only an estimate, assuming no other income — if you already have a salary or other income, the break-even point is lower. An accountant needs to calculate it from your real income.
This information is general guidance based on Revenue Department rulings (Kor Kor 0706/5764 · Kor Kor 0702/7726 · Kor Kor 0706/5864 · Kor Kor 0811/05502) It is not individual tax advice · InnoHome does not file tax on behalf of investors · For your own case you should consult an accountant, or request a ruling from the Revenue Department before deciding.
Every deal has avaluation bookto read before you put money in
We do not just tell you what the property is worth. We lay out where that number comes from — properties actually listed for sale in the same area, photos the team took themselves, and copies of the front and back of the title deed The example below uses illustrative data throughout
| Amount offered | ฿2,000,000 |
| Contract type | Mortgage, 1 year |
| Item | Amount |
|---|---|
| Appraised value | ฿4,000,000 |
| Amount lent | ฿2,000,000 |
| of the appraised value | 50% |
| Return per year | 15% |
| Comparable property | Price / sq. wah |
|---|---|
| Plot 1 · 400 m away | ฿38,000 |
| Plot 2 · 1.2 km away | ฿35,500 |
| Plot 3 · 2 km away | ฿41,000 |
| Plot 4 · adjoining project | ฿36,200 |
| Lowest / average | 35,500 / 37,675 |
- Cover — property type · amount · photos
- Analysis page — location · area · contract terms
- Market comparison — properties actually listed in the area
- Property photos — taken on site, not project renders
- Copy of the front of the title deed
- Copy of the back of the title deed — to see existing encumbrances
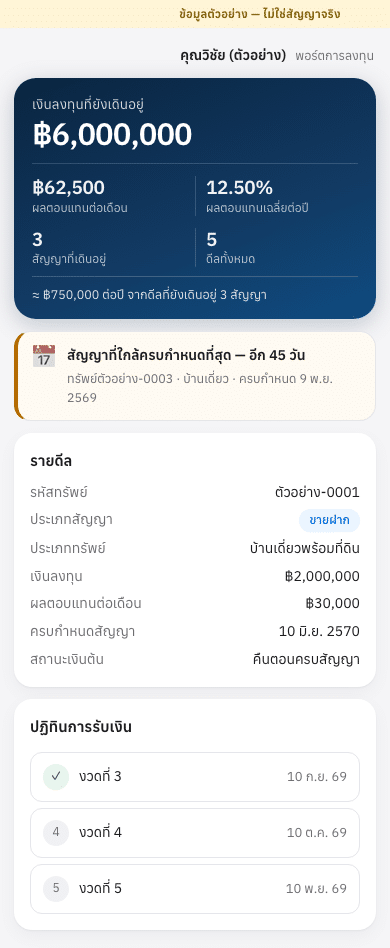
Seethe money that actually arrives each instalment without waiting for anyone to summarise it
Every deal you invest in has its own page, opened through LINE, viewable for the whole term of the contract. It is not a report sent to you once a month.
- Investment still running and the return per month
- The average return per year is calculated from your real deals not an advertised figure
- Payment calendar which instalments have arrived and which have not
- Advance reminderswhen a contract is approaching its end
- The deal’s documents can be opened from inside the system
The contract documents you already have a legal right to can be downloaded from here, without asking each time
From the first conversation to the first return payment
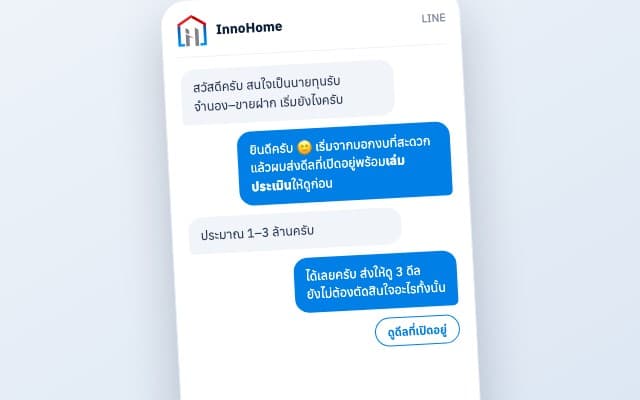
Talk to the team
Tell us the amount you are interested in and the risk you can accept. Nothing to transfer yet
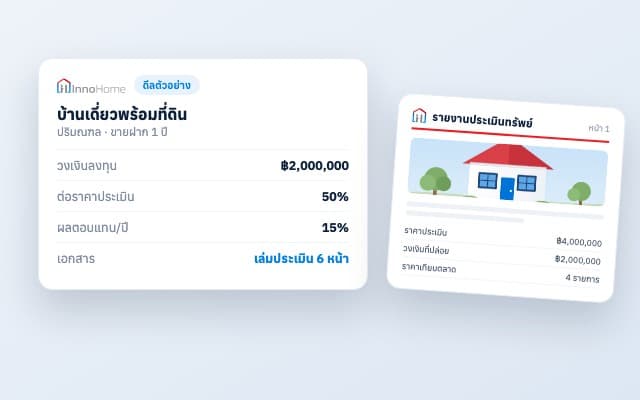
See the deal with its documents
See the appraised value, the title deed and what happens if the property is lost, before you decide
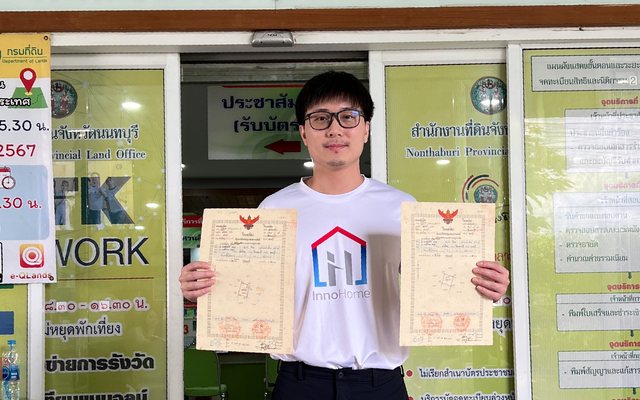
Transfer at the Land Office
Done in front of an officer, with ownership registered the same day
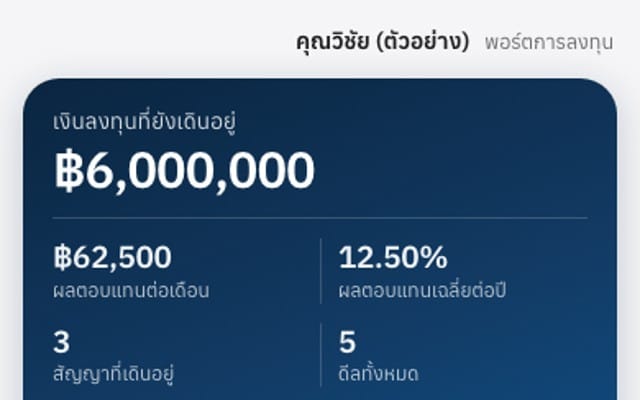
Watch the instalments in the portal
You see each instalment arrive yourself, with no phone calls
What investorsalways ask before putting money in
What is the minimum to start
If your capital is below this, tell the team. We will look at whether there is a deal that fits your amount at that time but we will not promise there will be one every month because it depends on the properties that actually come in
During the contract, who owns the property, and can I go and use it
so you cannot go and use it — A mortgage is security, not a transfer of ownership the borrower keeps the property and keeps living in or using it as normal your right is to be repaid, and if they default, to have the property sold so that you are repaid
⚠️ You cannot take the property yourself if they stop payingthe mortgage has to be enforced through the court — Section 728 of the Civil and Commercial Code. It takes time and it costs money, which is why we negotiate long before the deadline
This is the main difference from lending where ownership is transferred at the start
If the borrower does not redeem, do I have to chase them myself
⚠️ Butselling takes time, and the price achieved depends on the market at that time We do not guarantee that it will sell within any period or at any particular price See all 4 steps of the plan
Can I withdraw midway if I suddenly need the money
Is the 9-15% per year return guaranteed
This is not a deposit, and there is no protection of principal
How much does InnoHome charge the investor
The costs on the borrower’s side (our commission, based on the loan amount, · Land Office fees) are deducted from what the borrower receives, and are written out in full in the quotation the borrower sees before signing They are not deducted from your money
Is the return taxable
⚠️ The point people get wrong most often is that the interest ceiling is 15% per year under Section 654, and charging above it makes the whole interest void, not just the excess so you should keep evidence of cost for every deal from day one — Read the full investor tax summary
This is general guidance based on Revenue Department rulings, not individual advice · InnoHome does not file on your behalf. For your own case, have an accountant review it before filing
Do I have to go to the Land Office myself
The property is in another province. Do I have to go and see it myself
Get afree sample valuation book
and book a private call
This page is not meant to close a sale — it is meant to let you understand how this business works and where the risks are We only ask for your name and phone number. The rest is our job, to explain it clearly.
- The full sample valuation book (8-page PDF) See what the valuation team based the price on, before you believe anyone’s numbers
- A 30-minute private consultation — at no cost Ask anything you do not yet understand. By phone or on LINE, whichever you prefer There is no pitch to invest on that call
- Deals currently open for funding You can just look. There is nothing you have to answer.
If you are not sure, it is better not to invest yet
Get a free sample valuation book, or book a private 30-minute call — no obligation, and no pitch to invest on the call
Talk to the team on LINE Get the free valuation book